Digital banking is transforming the way customers interact with their finances. With the rise of fintech and the widespread adoption of online and mobile banking, traditional banking practices are being challenged. The convenience and accessibility of digital banking are reshaping customer behaviour, leading to increased preference for real-time transactions and personalised financial services.
As customers embrace these digital solutions, their expectations evolve. They now seek seamless, efficient banking experiences that allow for instant access to services at their fingertips. This shift has pushed banks and financial institutions to innovate continuously and cater to a more tech-savvy clientele.
The impact of digital banking is not just about convenience; it influences spending habits, savings strategies, and even investment choices. Customers are becoming more informed and engaged, leading to a greater focus on financial literacy and responsible financial management. This evolving relationship with money underscores the significant role that digital banking plays in modern financial behaviour.
Digital Banking Transformation
Digital banking is significantly transforming how consumers interact with financial services. This evolution encompasses advancements in technology, operational efficiency, and the emergence of new digital platforms that reshape customer experiences.
The Evolution of Digital Banking
The shift from traditional banking to digital banking began in the 1990s with online banking services. Initially, this involved basic functionalities like balance inquiries and fund transfers.
With ongoing digital transformation, banks now offer comprehensive services through user-friendly apps. Features like mobile deposits, budgeting tools, and personalised financial advice have become standard. Digital-only banks have disrupted the market, attracting customers with lower fees and enhanced convenience.
The evolution reflects the industry’s shift towards innovation, as banks adapt to customer expectations for speed and accessibility. This change has positioned digital banking as a primary channel for financial transactions.
Digital Disruption in the Banking Sector
Digital disruption has redefined the banking landscape, driven by rapid technological advancements. Incumbent banks face intense competition from fintech companies that leverage technology to offer flexible and innovative services.
This competition has prompted traditional banks to adopt digital strategies to retain customers. Features like AI-driven chatbots for customer support and real-time transaction alerts enhance the customer experience.
As consumers embrace these technologies, their behaviour shifts towards expecting instant services and seamless digital interactions. This disruption also encourages banks to streamline operations, resulting in improved efficiency and cost savings.
The Role of Fintech
Fintech companies have emerged as key players in the financial services arena. They provide specialised solutions that traditional banks often struggle to match. These innovations enhance customer engagement and streamline processes.
Fintech solutions range from peer-to-peer lending platforms to investment apps, showcasing diverse offerings. By integrating advanced technology, fintech enhances operational efficiency and reduces service delivery time.
The collaboration between banks and fintechs is also noteworthy. Many traditional institutions partner with fintech companies to enhance their digital capabilities, offering customers a more comprehensive suite of services. This synergy signals a shift towards a more integrated approach to financial services.
Enhancing Customer Experience
Digital banking enhances customer experience through tailored engagements, seamless interactions, and advanced technologies. These factors collectively contribute to a more personalised and convenient banking environment.
Personalisation and Customer-Centric Approaches
Personalisation in digital banking is transforming customer engagement. Banks increasingly utilise data analytics to offer customised product recommendations based on individual behaviours and preferences.
Customers receive tailored communications that resonate with their specific financial needs. This focus on hyper-personalisation fosters loyalty and enhances satisfaction.
Features like customised dashboards and alerts cater to individual financial goals, providing a more intimate banking experience. Ultimately, these personal touches lead to stronger relationships between customers and their banks.
Omnichannel Experiences and Customer Convenience
A robust omnichannel experience is essential in modern banking. Customers now expect seamless transitions between online and offline channels, ensuring convenience at every step.
Digital banking platforms allow customers to manage accounts via mobile apps, websites, or in-branch services. This flexibility caters to diverse customer preferences and lifestyles.
Integration across channels ensures that customers can continue their transactions without disruption. Consequently, their experiences become smoother, leading to increased engagement and satisfaction.
The Emergence of AI and Chatbots
Artificial Intelligence (AI) and chatbots play a pivotal role in enhancing customer service within digital banking. These technologies provide instant support and can handle numerous inquiries simultaneously.
Chatbots are programmed to assist with common questions, transactions, and even complex financial advice. They empower customers to receive assistance at any time, eliminating long wait times typically associated with traditional banking.
AI also analyses customer interactions, enabling banks to optimise services further based on behavioural insights. This proactive approach enhances the overall experience, making banking more efficient and user-friendly.
Risk Management and Security
Digital banking has transformed how institutions approach risk management and security. Effective measures are critical to maintaining customer trust and ensuring the protection of sensitive data.
Cybersecurity Measures in Digital Banking
Cybersecurity is a cornerstone of digital banking, guarding against various online threats. Banks implement robust multi-layered security protocols, including firewalls, intrusion detection systems, and encryption technologies.
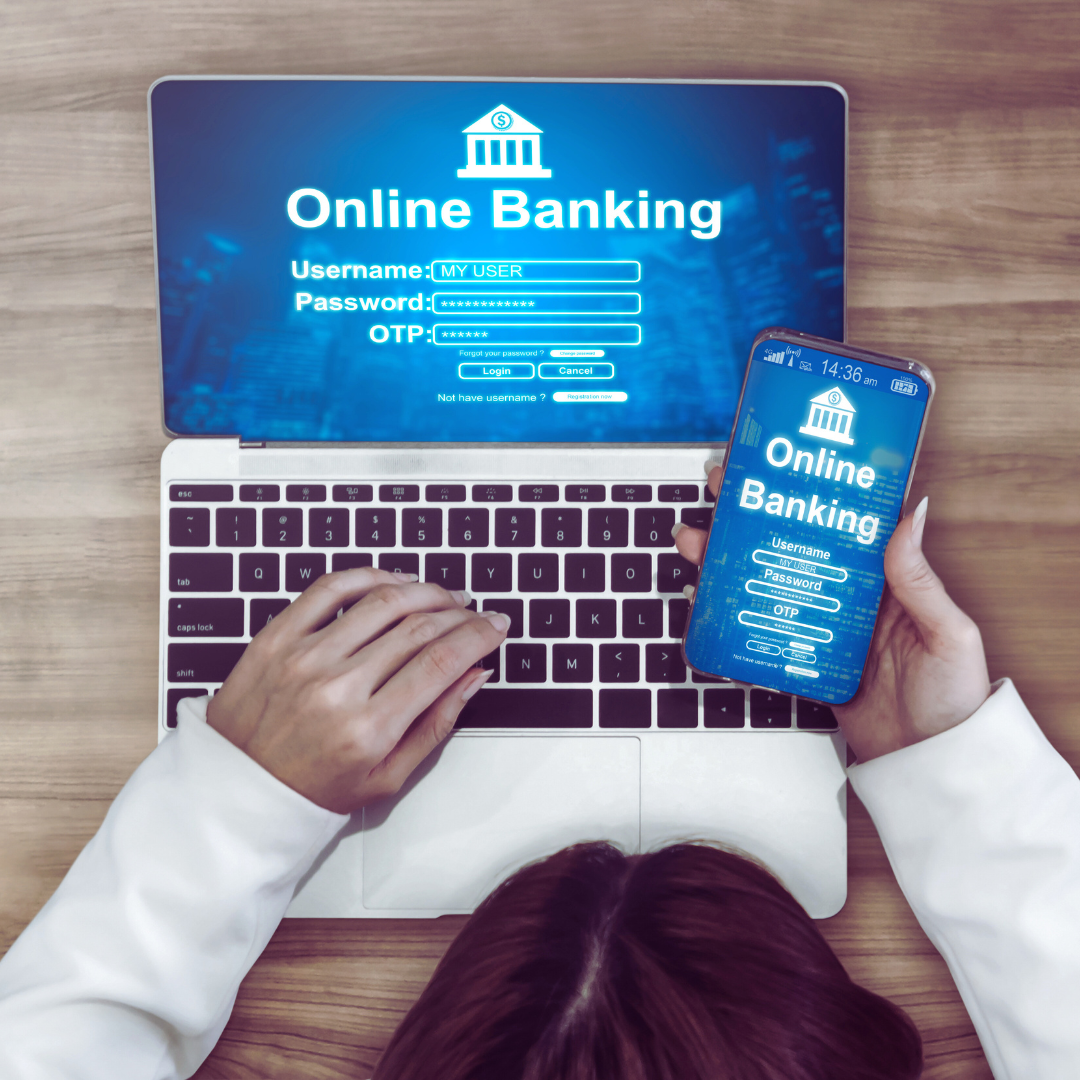
Two-factor authentication (2FA) has become a standard feature, requiring users to provide two forms of identification before accessing accounts. This measure significantly reduces the risk of unauthorised access.
Additionally, institutions regularly conduct security audits and penetration testing to identify vulnerabilities. Ongoing employee training on phishing and social engineering tactics also helps create a knowledgeable workforce prepared to counteract cyber threats.
Data Privacy and Protection
Data privacy is a critical concern in digital banking. Institutions are mandated to safeguard personal information, adhering to regulations such as the GDPR in the UK. This regulation requires transparent data handling practices and the explicit consent of customers for data collection.
To protect data, banks employ techniques such as data masking and anonymisation. Secure backups and disaster recovery plans are also in place to mitigate data loss in the event of a cyber incident.
Customers are encouraged to take proactive steps, such as regularly updating passwords and monitoring account activities for any signs of fraud. Institutions’ commitment to data protection helps foster trust among customers.
Compliance and Regulatory Perspective
Compliance with regulatory standards is essential for digital banking institutions. Authorities set stringent guidelines to ensure that banks manage risks effectively and protect consumer data.
The Financial Conduct Authority (FCA) and other regulatory bodies oversee adherence to these standards. Banks must regularly submit compliance reports and undergo audits to demonstrate their security measures’ effectiveness.
Failure to meet these requirements can result in significant penalties and damage to reputation. Institutions invest in compliance training and technology to ensure they remain aligned with evolving regulations, thus reinforcing their commitment to security and trust.
The Future of Digital Banking
The landscape of digital banking is evolving rapidly, driven by technological advancements and changing consumer expectations. Key developments in predictive analytics, blockchain technology, and emerging innovations will play pivotal roles in shaping customer behaviour and the banking experience.
Predictive Analytics and Data-Driven Insights
Predictive analytics leverages big data to enhance customer experience in digital banking. By analysing past behaviour, banks can anticipate customer needs and preferences. This approach allows for personalised services like tailored product recommendations and proactive support.
Banks utilise AI to refine data processes and deliver insights. Machine learning algorithms can identify patterns in transaction data, enabling banks to mitigate risks and improve security. By understanding customer behaviour, banks foster trust and long-term relationships.
Data-driven strategies greatly enhance marketing effectiveness. By leveraging Market research, banks can better understand customer preferences, behaviours, and emerging trends, allowing targeted campaigns to achieve higher engagement and conversion rates. Partnering with experienced customer experience specialists ensures these insights are translated into practical strategies that not only boost satisfaction but also strengthen long-term customer relationships, ultimately shaping the future of modern banking.
Blockchain Technology and Financial Inclusion
Blockchain technology offers transformational potential for digital banking and financial inclusion. Its decentralised nature facilitates secure, transparent transactions without intermediaries. This reduces costs and enhances access for underserved populations.
By utilising blockchain, banks can streamline know-your-customer (KYC) processes, enabling quicker onboarding. This innovation accelerates access to banking services for those lacking traditional identification.
Furthermore, blockchain supports smart contracts, ensuring the automatic execution of agreements, and thus fostering trust. As financial barriers diminish, more individuals can participate in the global economy, allowing banks to reach a broader audience.
Emerging Technologies and Innovations
Emerging technologies continuously reshape the digital banking landscape. Cloud computing offers scalable solutions, allowing banks to manage data efficiently while enhancing security. This flexibility supports rapid adaptation to market demands.
The Internet of Things (IoT) plays a role as well, connecting devices to streamline banking processes. For instance, smart devices can facilitate seamless payments and enhance customer interactions.
Innovations such as chatbots powered by AI improve customer service by providing instant support. These advancements not only enhance user experience but also free up human resources for complex tasks. As these technologies evolve, they are set to redefine the future of banking.